Novaluxia PH Withdrawal Checklist: Set Your Cash-Out Up Right
Most withdrawal hiccups come down to three everyday items: an ID that has expired, a bank card that has been reissued, or a minimum and processing window printed on the screen. This checklist sets all of it up before you tap, and shows where to check status if a request is taking a while.
If you typed "novaluxia withdrawal problem" or "can't withdraw" into a search bar, the good news is that almost every case traces back to a small, fixable item on the account screen. The cash-out route itself is ordinary: real-name verification, an accepted Philippine ID, a bank card you still hold, and a processing window the screen states before you send anything. Set those four up correctly and a withdrawal tends to move the first time.
This page is the pre-flight version. It gathers the checklist, the three everyday snags and the place to check status into one route you can run in a few minutes. If you are searching "hindi makapag withdraw," start at the checklist below and work down.
Run the pre-flight checklist#
Work through these five items in order before you tap Withdraw. Every one of them is visible on a screen inside the app, and every one of them speeds the request up.
| Check | Where it lives | What "ready" looks like |
|---|---|---|
| Account in good standing | Verification and account screens | Verification reads complete and no account notice is pending |
| ID valid today | Verification section | An accepted Philippine ID, unexpired now, name matching the account |
| Bank card bound | Bank-card binding | The card displayed is one you still hold and still use |
| Minimum met | Withdrawal screen | The balance is at or above the stated minimum |
| Window understood | Withdrawal screen | You know the processing time printed on the page |
Five items, all on the account side of the app. When each reads correctly, the request has somewhere real to land and nothing left to stall on.
The accepted IDs and the bank-card binding#
The verification screen lists the documents the app accepts, and the list is the standard set for a Philippine money flow: passport, UMID, Postal ID, National ID (PhilSys) and TIN ID. Two details carry the weight. The ID must be valid today, not merely valid on the day you uploaded the photo, and the name on it must match the account name exactly. The second half of verification is the bank-card binding: whatever card is attached to the account must be one you still hold, because that is where the payout is sent.
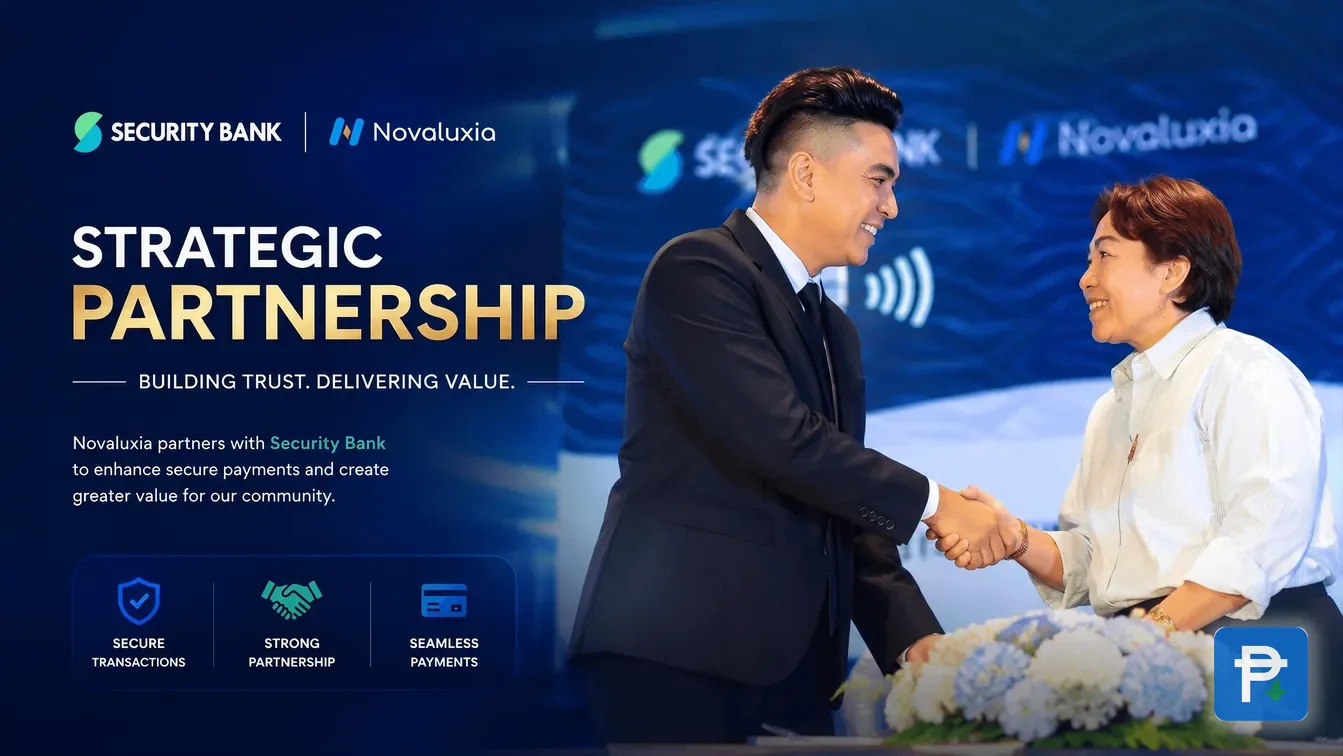
This is not an obstacle course. A payout that lands in a Philippine bank moves over a licensed rail, and a licensed rail means the institution at the other end applies the same know-your-customer step as anywhere else. The platform's own announcement of a Security Bank strategic partnership, dated 20 May 2026, sits on its public news list and anchors that route. Real-name verification is what a bank-grade cash-out looks like, which is precisely why finishing it early pays off.
The company behind the route keeps a record anyone can check: 105+ merchant partners, 3M+ group-buy sales and 99% positive feedback on its own pages, incubation by Innoventure Global Partners Ltd, and a Philippine operation run from a Makati regional headquarters with local warehousing and support. A cash-out attached to a platform with that public footprint is one you can look up before you send anything.
The good news is that verification is a one-time setup. Once it reads complete and the card binding is current, both stay done until a document or a card expires. The top-up and wallet guide follows the same account screen from the other direction, so the two sides of the wallet read as one system.
The processing window and what affects it#
The withdrawal screen states two numbers that decide when a request moves: the minimum you can send and the processing window that applies. Both belong to the day you make the request, and both are printed before the button is pressed, so there is never a need to guess at withdrawal time.
Once a request is in, ordinary banking rhythms take over. Requests sent late in the day, on weekends or over a holiday can sit until the next banking day, exactly as they would with any transfer between institutions. A verification detail that is not yet complete can hold a request at the starting line, which is why the checklist comes first. None of that is unusual, and none of it is permanent: fix the item, send again, and the window restarts from the moment everything is clean.
The routine we recommend is simple. Check the two numbers on the withdrawal screen, send the request, note the date and the stated window, and let the app report the outcome rather than watching the clock. That is the entire timeline, and it is published in advance.
The three everyday snags, and how each clears#
Nearly every request that sits waiting is one of three things, and each has a fix inside the app.
- The ID has expired since it was uploaded. Documents have dates, and a file that was valid last year can fail today. The fix: take a bright, current photo of an accepted, unexpired ID whose name matches the account, re-upload it in the verification section, and wait for the screen to read complete.
- The bank card was reissued. Banks replace cards when they expire or get lost, and a replacement can break the binding. The fix: open the bank-card binding, remove the old card and add the one you hold now, then double-check the card number on the screen matches the card in your hand.
- The minimum or the window has not been met. A request below the stated minimum will not send, and one sent a moment ago may still be inside its processing window. The fix: reach the minimum if needed, then allow the window printed on the screen to pass before checking again.
Three causes, three fixes, and no support ticket required for any of them. That is the value of running the checklist first: it clears the ordinary cases in the time it takes to read the screen.
If a withdrawal problem shows up, where to check status#
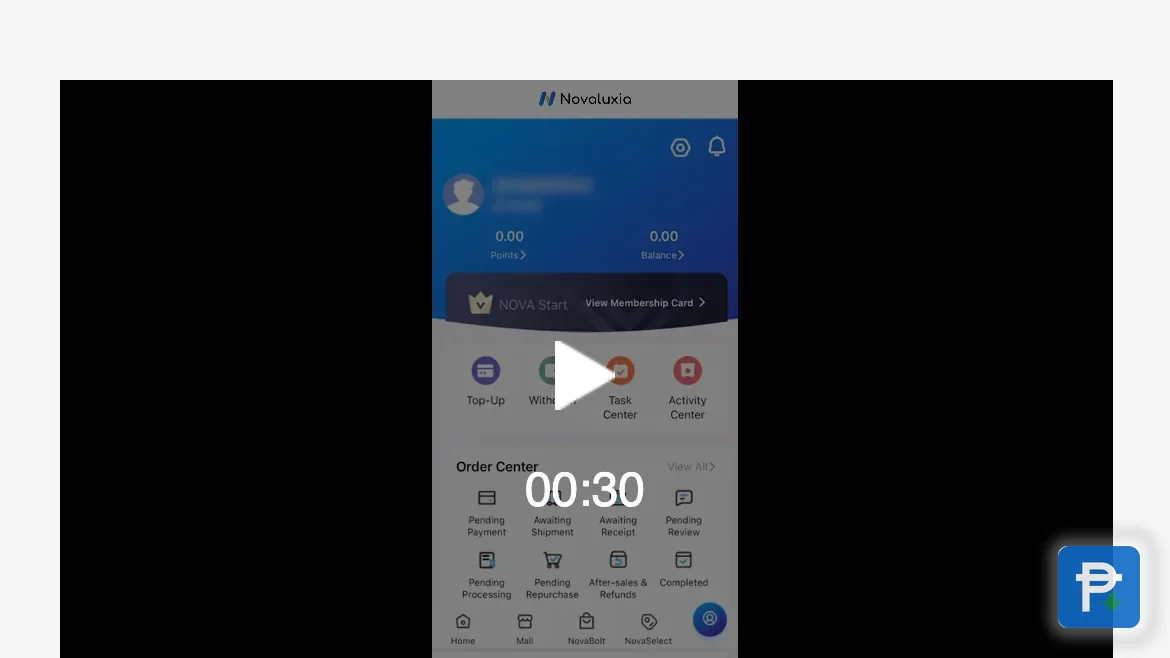
Start with the screens. The account screen shows the wallet balance and the Withdrawal entry beside Top-Up. The verification section shows whether the real-name step reads complete. The bank-card binding shows which card is attached. The withdrawal screen shows the minimum and the window in force, plus the record of what you sent and when.
If all four check out and the request is still not moving, the next step is the in-app support channel, because that is the channel that can act on it. In-app support can open the request, trace the transaction and move it forward, all from the same account that holds the verification and the bank binding. Raise one ticket inside the app and keep the number close. That number is how a request gets followed up, and it is the only place a follow-up needs to happen.
The full withdrawal walkthrough covers the same flow screen by screen if you want the longer read, including the guide-tab documents and dates that sit behind it.
Paying outside the app: how the tricks work#
One more routine belongs on this page, because the cash-out side is where fake "agents" gather. The offer usually arrives in a chat or a comment: someone says they can unblock a withdrawal for a fee, speed a request along, or "release" your balance if you send a payment first. Some ask for an OTP to confirm the account. Every version of it is a trick, and none of it is the platform. A withdrawal runs inside the app, to the bank card you bound yourself, with the minimum and the window printed on screen. No legitimate cash-out needs a fee, an agent or a code handed to a stranger.
The same rule covers a copycat app or a file sent through a chat. Install from the store listing you found by searching, and match the identifiers: package uni.UNI7878C48 on Google Play and id 6746707874 on the App Store. The fake apps and pages guide collects the one-minute checks and the first steps to take if money has already moved outside the app.
Set the account up right and the cash-out side is quiet: a verified name, a current card, a stated window, and a record in the app. That is a payment route built for tracing, and it is ours to keep tidy.
Next#
- The record with its dates: our evidence file
- What every order status means: order tracking in the Philippines
- The full 2026 assessment: our Novaluxia review
- Every review and check we keep: the reviews hub
What we checked, and when#
- The checklist items (verification status, accepted ID list, bank-card binding, minimum and processing window): read on the verification and withdrawal screens in the app, 2026-09-18.
- The Security Bank strategic partnership dated 20 May 2026: from the platform's own news announcement, checked 2026-09-18.
- Store identifiers and the official channels: from the Google Play and App Store listings and the official sites, 2026-09-18.
- The guide-tab documents behind the account flow: read in the app's guide section, 2026-09-18.
Requirements and windows can change, so open the withdrawal screen and read the numbers before you send a request. Our recommendation: finish verification once, keep the card binding current, note the window, and let the in-app support channel handle anything that needs a push.
Quick answers
- Why would a Novaluxia withdrawal take a while?
- The usual reasons are an ID that has expired since it was uploaded, a bank card that has been reissued and no longer matches the binding, or a minimum and processing window stated on the withdrawal screen that has not yet passed. Each one is fixed inside the app, and the checklist on this page covers all three.
- Which ID does the app accept?
- The verification screen lists a passport, UMID, Postal ID, National ID and TIN ID. The document needs to be valid today, not only on the day it was uploaded, and the name printed on it has to match the account name.
- What do I do if a request is stuck?
- Work the checklist first, then open a support ticket in the app and keep the number. In-app support can see the request, trace it and push it along, because the withdrawal, the verification and the bank binding all sit on the same account.
- Is there a fee to unblock a withdrawal?
- No. The withdrawal runs inside the app to the bank card you bound yourself, and the screen states the minimum and the processing window before you send anything. Anyone outside the app charging a fee to release a cash-out is running a separate trick.